 Digitnomics
African fintech companies are pushing for a common regulatory framework that would allow licensed payment firms to expand across African markets without having to start the licensing process from scratch in every country.
The proposal, known as licence passporting, is emerging as a key part of efforts by the African Union Commission (AUC) and AfricaNenda Foundation to harmonise regulations governing cross-border digital payments.
The initiative seeks to address one of the biggest obstacles to fintech expansion on the continent — fragmented regulatory systems that require companies to navigate separate licensing and compliance processes in each market.
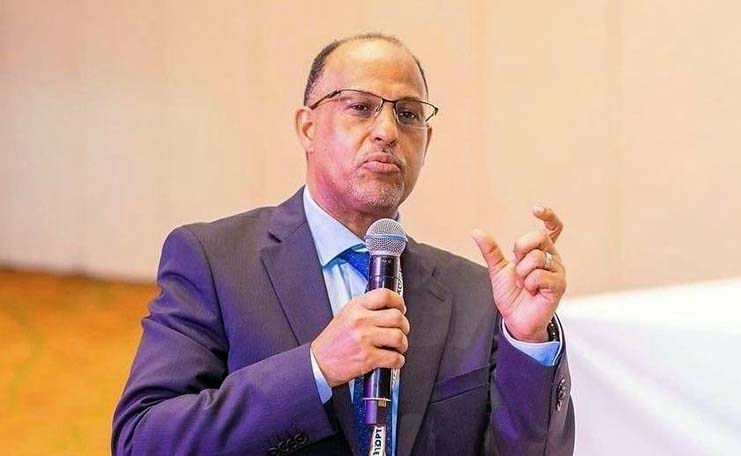
Dr. Patrick Conteh, Chief Executive Officer, Africa Fintech Network, said Africa already has much of the technological infrastructure required to support a connected digital payments ecosystem, but regulatory fragmentation remains a major barrier.
He said a fintech licensed and supervised in one African country currently has to undergo another licensing process when it seeks to enter another market.
“If you’re in Ghana, you’re licensed and provided by Central Bank of Ghana, you want to go to Nigeria, you start from zero. You start the process afresh. You want to go to Gambia, you start zero, you start the process afresh,” Conteh said.
According to him, Africa needs a common regulatory rulebook that would make it easier for licensed payment service providers to access other African markets.
“What we see is an attempt, or efforts, at defining a common rulebook, which is really good, and it’s doable. Africa needs that common rulebook,” he said.
Licence Passporting
Under the proposed licence-passporting model, a fintech licensed in one participating African country could potentially use that licence as the basis for operating in another participating jurisdiction, subject to agreed standards, safeguards and regulatory oversight.
Conteh said the African Fintech Network had already begun work around the concept, including discussions with banking supervisors across the continent.
He disclosed that the network had presented the proposal to the Committee of African Banking Supervisors, an arm of the Association of African Central Banks, with supervisors from about 40 central banks involved in the discussions.
A technical working group was subsequently established to examine the proposal, while further consultations have been held with industry stakeholders and central banks.
The objective is to create a regulatory mechanism that would allow Africa’s growing digital payment infrastructure to support genuine cross-border expansion by fintech companies.
“Africa has technical wheels,” Conteh said, pointing to the rapid development of instant payment systems and mobile money across the continent.
“The infrastructure, the building, and their scaling very, very fast. So that’s not the problem. As she said, the binding constraint is the fragmentation of rules, the regulations.”
Regulatory Fragmentation
The push for licence passporting comes as African countries continue to invest heavily in instant payment systems, mobile money and other digital financial infrastructure.
However, fintech companies expanding across borders can face different licensing requirements, compliance obligations, consumer-protection rules and supervisory processes in every new market.
For growing fintech companies, the duplication can increase the cost and time required to enter new countries and make it harder for businesses to scale beyond their home markets.
A harmonised licensing framework could potentially reduce those barriers by allowing firms that have already met regulatory requirements in one jurisdiction to enter other participating markets through a streamlined process.
It could also increase competition among payment providers and expand access to digital financial services for consumers and businesses.
Broader Regulatory Harmonisation
Licence passporting is being developed alongside a wider regulatory harmonisation initiative supported by the AUC and AfricaNenda.
The broader framework seeks convergence in areas including licensing and passporting, interoperability standards, anti-money laundering and customer due diligence, consumer protection, data governance, supervisory cooperation, and settlement and liquidity arrangements.
Jacqueline Jumah of AfricaNenda Foundation said consultations had extended beyond governments and central banks to include fintechs, private-sector operators and other participants in the digital payments ecosystem.
She said regional consultations had been held in Johannesburg, Kigali, Abidjan and Lagos, with further engagement planned in North Africa.
According to Jumah, the objective is to ensure that the proposed framework reflects the realities of the different players operating within Africa’s digital payments ecosystem.
Dr. Patrick Olomo of the African Union Commission also stressed the importance of bringing fintechs and other private-sector players into the process, given their growing role in Africa’s financial ecosystem.
Nigeria, Ghana Could Provide Starting Point
Nigeria and Ghana have emerged as potential starting points for aspects of the broader framework because their national payment switches are already interconnected.
According to AfricaNenda, countries with relatively mature instant payment systems and existing cross-border connections could provide a starting point for testing regulatory convergence.
However, the initiative is expected to adopt a readiness-based approach because African countries remain at different stages of digital financial development.
For fintech companies, the potential impact of licence passporting could be significant.
Instead of spending months navigating separate regulatory processes and compliance requirements in every new market, companies could potentially use an existing licence as the basis for expansion into other participating jurisdictions.
This could lower market-entry costs, shorten expansion timelines and allow African fintechs to scale across multiple countries more rapidly.
It could also support greater competition and innovation in digital financial services while making it easier for consumers and businesses to access payment solutions across borders.
The emerging debate therefore shifts the focus from whether Africa has the technology to support cross-border digital payments to whether its regulatory systems can keep pace.
Africa has been building the digital infrastructure for a connected payments market. The next challenge is creating rules that allow fintech companies to use that infrastructure across borders — and compete as continental businesses rather than country-by-country operators.
 Chinenye Anuforo